The Mortgage Market's Interest Rate Dilemma
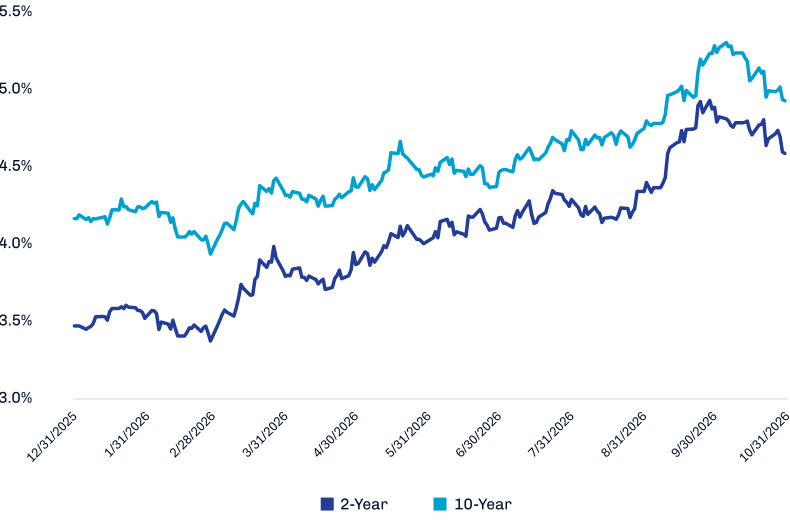
Interest-rate volatility has been a defining feature of fixed-income markets in 2026, with the mortgage market
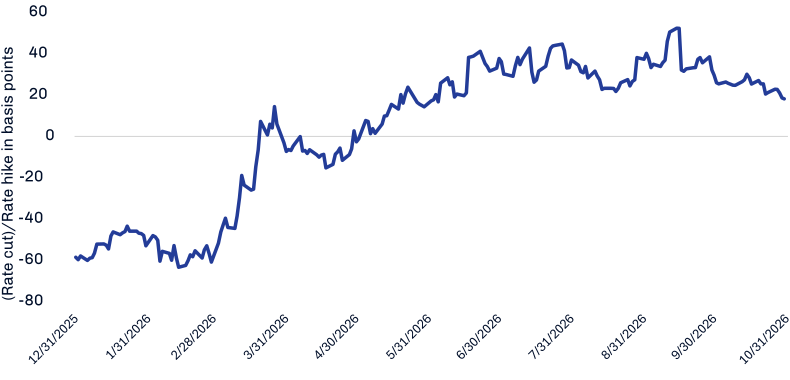
experiencing particularly pronounced effects. Expectations for Federal Reserve policy have shifted dramatically since
the beginning of the year, moving from anticipated rate cuts to a more hawkish outlook following the Fed's first rate
increase since 2023 in September (Exhibit 1). Persistent inflationary pressures, driven in part by rising energy
prices associated with the conflict in Iran and concerns surrounding the ongoing AI infrastructure buildout, have
complicated the outlook for monetary policy.
While rising interest rates create near-term challenges for fixed-income investors as bond prices decline, higher
yields can also provide greater income opportunities over time. As discussed in a recent insight, Rising Rates:
Lessons from 2022, an
important distinction between the historic fixed-income market selloff of 2022 and the current environment is the
substantially higher starting yield entering 2026. This additional income provides a greater cushion against rising
rates than investors experienced four years ago.
Despite this improved starting point, the impact of higher rates has not been uniform across fixed-income sectors.
Agency mortgage-backed securities (MBS) have been particularly sensitive to changing interest-rate expectations
(Exhibit 2), reflecting the unique prepayment and extension risks embedded in these investments. At the same time,
elevated mortgage rates have reinforced the housing market's lock-in effect, discouraging homeowners from selling or
refinancing and further complicating the outlook for mortgage investors.
Together, these dynamics highlight both the challenges facing the mortgage market and the importance of understanding
how different mortgage structures respond to changing interest-rate conditions.
Exhibit 1. Yields on 2-Year and 10-Year Treasuries Year to Date
Source: Bloomberg, data as of October 31, 2026.
Exhibit 2. Market Expectations for Federal Reserve Action by Year-End 2026
Source: Bloomberg, data as of October 31, 2026.
Mortgages as an Investment
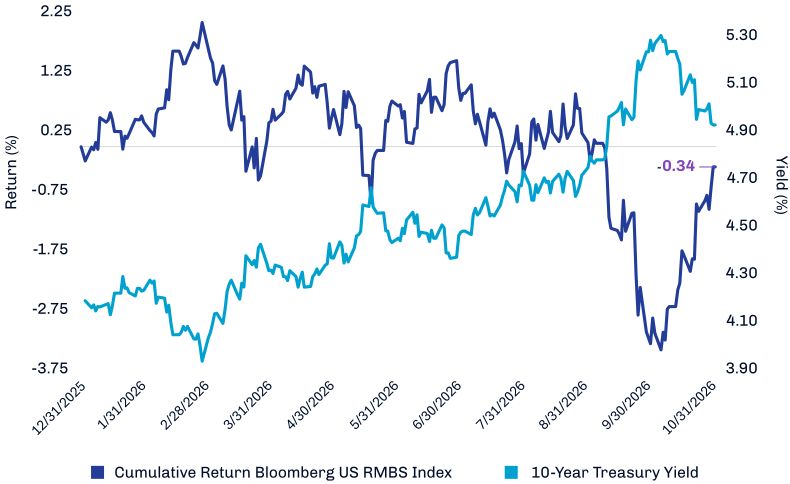
As rates have pushed higher across the yield curve in 2026, the mortgage market (as measured by the Bloomberg US MBS
Index) has experienced greater pressure than other areas of the market such as asset-backed securities, investment
grade corporate debt and commercial mortgage-backed securities. Agency passthrough mortgages carry a higher
sensitivity to interest rate movements as the optionality that they carry adjusts to the current interest rate
environment. When rates move higher, mortgage holders are less likely to refinance and pay off their current mortgage,
thus extending the life of the mortgage and increasing duration or sensitivity to interest rate movements. Conversely,
when rates drop, homeowners will look to refinance out of a higher mortgage rate, paying off their mortgage and
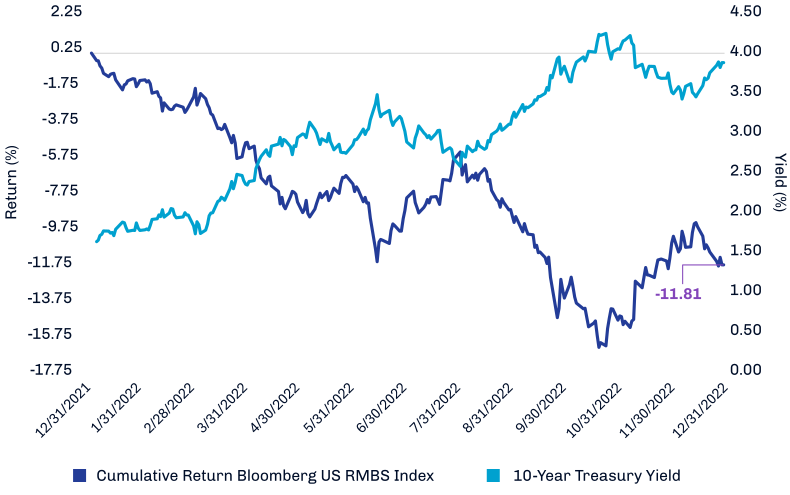
saddling investors with excess cash in a lower rate environment. Exhibit 3 illustrates how the shift in interest rates
in 2026 has impacted the cumulative return of the Bloomberg US MBS Index and Exhibit 4 provides a comparison to market
movements in 2022.
Exhibit 3. 2026 Illustrates the Impact of Rates Moves on Mortgages
Source: Bloomberg; data as of October 31, 2026.
Exhibit 4. 2022 Was a Different Story
Source: Bloomberg; data as of October 31, 2026.
An examination of the Bloomberg US MBS Index illustrates how the mortgage market has shifted over the last 20 years,
with rising interest rates driving a substantial shift into higher-coupon mortgages. Exhibit 5 illustrates how the
mortgage market has evolved over time, highlighting a pronounced shift into higher-coupon mortgages over the past 10
months. With the current national 30-year mortgage rate above 7%, expectations for any kind of prepayment wave for the
mortgages held in the index are highly unlikely. This is most apparent when we break down the overall mortgage market,
not just mortgages held in the index. The share of index MBS with coupons of 5% or higher increased from approximately
32.1% in 2025 to 37.4% in October 2026, illustrating how the composition of the agency MBS market is gradually
shifting toward higher-coupon mortgages, even as lower-coupon mortgages remain a substantial portion of the
index.1
Exhibit 5. Mortgage Coupon of Index Mortgage-Backed Securities
|
Coupon
|
2006
|
2016
|
2025
|
October 2026
|
|
2.0%
|
0.0%
|
0.6%
|
21.9%
|
19.9%
|
|
2.5%
|
0.0%
|
6.5%
|
16.5%
|
14.8%
|
|
3.0%
|
0.0%
|
30.3%
|
10.4%
|
9.2%
|
|
3.5%
|
0.1%
|
30.3%
|
7.6%
|
6.9%
|
|
4.0%
|
2.2%
|
17.2%
|
6.1%
|
5.7%
|
|
4.5%
|
9.5%
|
7.6%
|
5.5%
|
6.2%
|
|
5.0%
|
28.1%
|
3.8%
|
8.1%
|
11.8%
|
|
5.5%
|
31.3%
|
2.2%
|
10.8%
|
13.2%
|
|
6.0%
|
19.2%
|
1.3%
|
8.9%
|
8.7%
|
| 6.5% |
7.1% |
0.3% |
3.5% |
3.1% |
| 7.0% |
1.8% |
0.0% |
0.7% |
0.6% |
| 7.5% |
0.5% |
0.0% |
0.1% |
0.0% |
| 8.0% |
0.2% |
0.0% |
0.0% |
0.0% |
Source: Bloomberg; data as of October 31, 2026.
But is there an alternative to the volatility and uncertainty that comes with interest rate-sensitive mortgages? For
investors seeking exposure to the agency mortgage market while managing the impact of interest rate fluctuations,
collateralized mortgage obligations (CMOs), a special purpose entity that owns the mortgages in the pool and organizes
them into classes based on their risk profile, offer an alternative with distinct cash flow characteristics. Income
received from the mortgage pool is passed to investors based on a predetermined set of rules and those investors
receive money based on the specific slice of mortgages they are invested in (called a tranche). One of the most common
examples of this type of security is the planned amortization class (PAC), a tranche that receives a primary payment
schedule and is, to a certain extent, protected from both prepayment and extension risk.
The Golden Handcuffs of Mortgage Lock-In
Elevated mortgage rates have created an unprecedented lock-in effect in the US housing market, as homeowners with
historically low mortgage rates are reluctant to sell and take on substantially higher borrowing costs. An analysis of
data available from the Federal Housing Finance Agency’s National Mortgage database indicates that as of the end
of
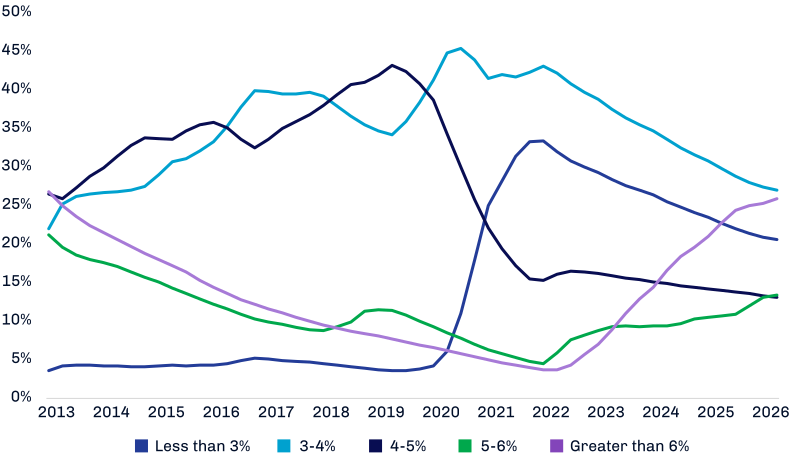
the second quarter 2026 (most recent data available), roughly 74.1% of outstanding mortgages in the United States
carry an interest rate below 6%, with nearly half of all mortgages below 4%. Exhibit 6 illustrates the shift in
outstanding mortgage coupon rates since 2013, with recent increases in mortgages carrying greater than 6% coupons due
to the shift higher in rates. With current mortgage rates hovering above 7%, the term “golden handcuffs”
describes the
reluctance of homeowners with significantly lower mortgage rates to move or refinance, given the prospects of
substantially higher borrowing costs.2
This dynamic has constrained housing supply, reduced mobility and contributed to elevated home prices despite higher
borrowing costs. By comparison, in early 2022, approximately 75.6% of mortgages were 4% or lower, yet refinancing
opportunities remained, with Bankrate.com’s U.S. Home Mortgage 30-year Fixed National Average at 3.27% at the
end
December 2021. Unlike previous tightening cycles, the magnitude and duration of the current rate increase have made
the lock-in effect particularly severe, with a meaningful decline in mortgage rates likely necessary to restore
housing market activity.3
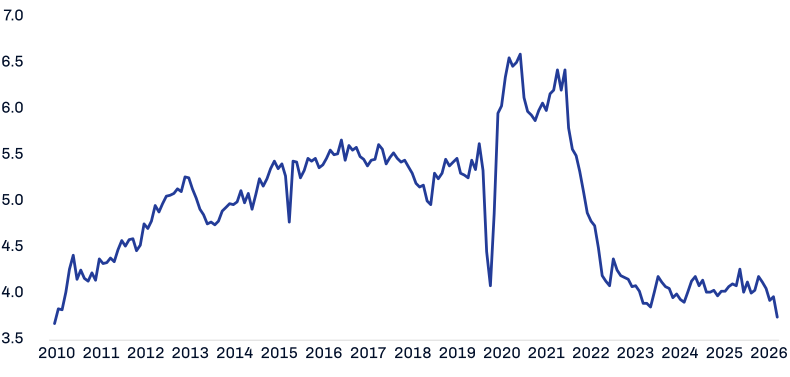
The October 2026 report from the National Association of Realtors showed a 5.5% decline in existing home sales to 3.75
million (Exhibit 7). This marks the strongest decline since January 2026 and the lowest activity level since August
2010, when the economy was still working through the housing bubble bursting and fallout from the financial crisis. On
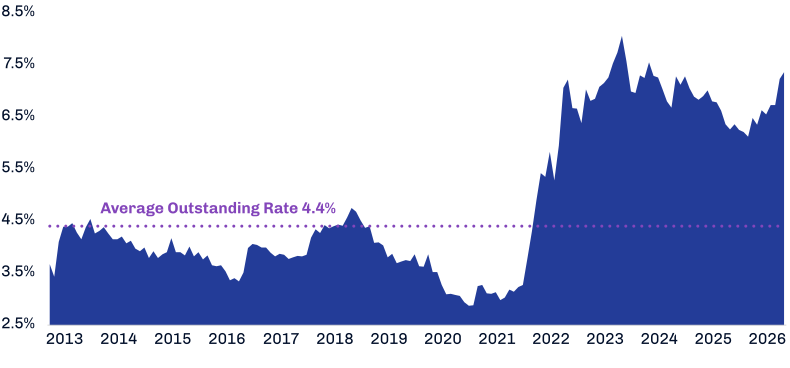
a year-over-year basis, sales dropped nearly 9% this year, the largest year-over-year drop since 2023. Exhibit 8
demonstrates the move higher in the 30-year fixed rate mortgage with the average outstanding rate of 4.4% since 2013,
exacerbating the golden handcuffs effect that discourages homeowners from moving.3,4
Exhibit 6. Shift in Outstanding Mortgage Interest Rates
Percent of Market Outstanding (%)
Source: FHFA, National Mortgage Database; data as of June 30, 2026.
Exhibit 7. Existing Home Sales
Millions of Sales
Source: National Association of Realtors, Bloomberg; data as of October 31, 2026.
Exhibit 8. Bankrate.com US Home Mortgage 30-Year Fixed Rate
Source: Bankrate.com, Bloomberg; data as of October 31, 2026.
The combination of elevated mortgage rates, limited refinancing incentives and constrained housing market activity
presents a challenging environment for mortgage-backed securities. With a substantial portion of outstanding mortgages
carrying coupons well below prevailing market rates, prepayment activity is likely to remain subdued unless interest
rates decline meaningfully. For investors, this reinforces the importance of managing extension risk and understanding
the cash flow characteristics of their mortgage exposure.
While traditional agency passthrough securities remain vulnerable to changes in interest-rate expectations, carefully
selected CMO structures, including planned amortization classes, may offer opportunities to achieve more predictable
cash flows within specified prepayment assumptions. In an environment where interest-rate uncertainty remains
elevated, security selection and an understanding of mortgage structure will continue to play an important role in
fixed-income portfolio construction.
1 Source: Bloomberg; data as of October 31, 2026.
2 Source: FHFA, National Mortgage Database; data as of June 30, 2026.
3 Source: Bankrate.com, Bloomberg; data as of October 31, 2026.
4 Source: National Association of Realtors, Bloomberg; data as of October 31, 2026.
The information contained in this material is provided by First Eagle Investment Management, LLC
(“FEIM”) and its global subsidiaries (collectively, “First Eagle”). FEIM is an investment
adviser registered with the US Securities and Exchange Commission (SEC). Registration with the SEC does not imply a
certain level of skill or training.
This material is for informational purposes only and reflects prevailing conditions and the judgment of the
author(s) as of the date of publication, all of which are subject to change. This material should not be relied upon
as investment advice; it does not constitute a recommendation to buy or sell a security or other investment; and it
is not intended to predict or depict the performance of any investment. This material is not being provided in a
fiduciary capacity and is not intended to recommend any investment policy or investment strategy or consider the
specific objectives or circumstances of any investor. We consider the information in this material to be accurate,
but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for
investment.
Prospective investors should inform themselves and consult with an investment, tax or legal professional as to any
applicable legal requirements, taxation and exchange control regulations in the countries of their citizenship,
residence or domicile that may be relevant prior to investing.
THIS MATERIAL DOES NOT CONSTITUTE AN OFFER OR SOLICITATION IN ANY JURISDICTION WHERE OR TO ANY PERSON TO WHOM IT WOULD BE UNAUTHORIZED OR UNLAWFUL TO DO SO.
All investments involve the risk of loss of principal.
Past performance does not guarantee future results, which may vary. The value of investments
and the income derived from investments will fluctuate and can go down as well as up. A loss of principal may occur.
Indexes are unmanaged and do not incur management fees or other operating expenses. One cannot invest directly in an index.
Collateralized mortgage obligations (CMOs) are a type of mortgage-backed security that organizes
mortgages based on maturity and risk levels.
Mortgage-backed securities (MBS) are debt securities whose payments of principal and interest are
backed by the cash flow generated by pools of mortgage loans.
Commercial mortgage-backed securities (CMBS) are debt securities secured by cash flows from
commercial real-estate mortgages.
Asset-backed securities (ABS) are debt securities whose payments of principal and interest are
backed by the cash flow generated by pools of income-producing credit assets.
Investment grade corporate bonds are debt securities issued by corporations perceived to have a
relatively low risk of default.
Bloomberg US Mortgage Backed Securities (MBS) Index (Gross/Total) measures the performance of
fixed-rate agency mortgage backed passthrough securities guaranteed by Ginnie Mae, Fannie Mae and Freddie Mac. A
total-return index tracks price changes and reinvestment of distribution income.
The information presented does not reflect the performance of any fund, strategy or account managed or serviced by
First Eagle, and there is no guarantee that investors will experience the type of performance reflected. There is no
guarantee that any market forecast set forth in this material will be realized. There is no guarantee that any
historical trend referenced herein will be repeated in the future, and there is no way to predict precisely when
such a trend will begin. The mention of specific securities is not a recommendation or solicitation to buy, sell or
hold any particular security and should not be relied upon as investment advice.
Availability of the products or services described may be restricted by law in certain jurisdictions. This material
may not be distributed, published or used by any person or entity in any jurisdiction or country where such
distribution or use would be contrary to local law or regulation.
United Kingdom
Napier Park Global Capital Ltd is authorised and regulated by the Financial Conduct Authority (FRN: 541427) in the
United Kingdom.
Middle East
This material is for information purposes only and has not been, and will not be, registered with or reviewed or
approved by any regulator located in the Middle East. It does not constitute or form part of any marketing
initiative, any offer to issue or sell, or any solicitation of any offer to subscribe to or purchase, any products,
strategies or other services, nor shall it, or the fact of its distribution, form the basis of, or be relied on in
connection with, any contract resulting therefrom. In the event that the recipient of this material wishes to
receive further information regarding any products, strategies or other services, it shall specifically request the
same in writing from an authorized financial adviser.
Canada
Pursuant to the international adviser registration exemption in National Instrument 31-103, First Eagle Investment
Management, LLC. is informing you that: (i) First Eagle Investment Management, LLC. is not registered in Canada and
is advising you in reliance upon an exemption from the adviser registration under National Instrument 31-103;
(ii) First Eagle Investment Management, LLC’s jurisdiction of residence is New York, USA; (iii) there
may be difficulty enforcing legal rights against First Eagle Investment Management, LLC. because it is a resident
outside of Canada and all or substantially all of its assets may be situated outside of Canada.
FEF Distributors, LLC (“FEFD”) (SIPC), a limited purpose broker-dealer, distributes certain First Eagle
products. FEFD does not provide services to any investor but rather provides services to its First Eagle affiliates.
As such, when FEFD presents a fund, strategy or other product to a prospective investor, FEFD and its
representatives do not determine whether an investment in the fund, strategy or other product is in the best
interests of, or is otherwise beneficial or suitable for, the investor. No statement by FEFD should be construed as
a recommendation. Investors should exercise their own judgment and/or consult with a financial professional to
determine whether it is advisable for the investor to invest in any First Eagle fund, strategy or product.
First Eagle Investments is the brand name for First Eagle Investment Management, LLC and its subsidiary investment
advisers. Diamond Hill is the brand name for Diamond Hill Capital Management, LLC, an investment adviser.
© 2026 First Eagle Investment Management, LLC. All rights reserved.